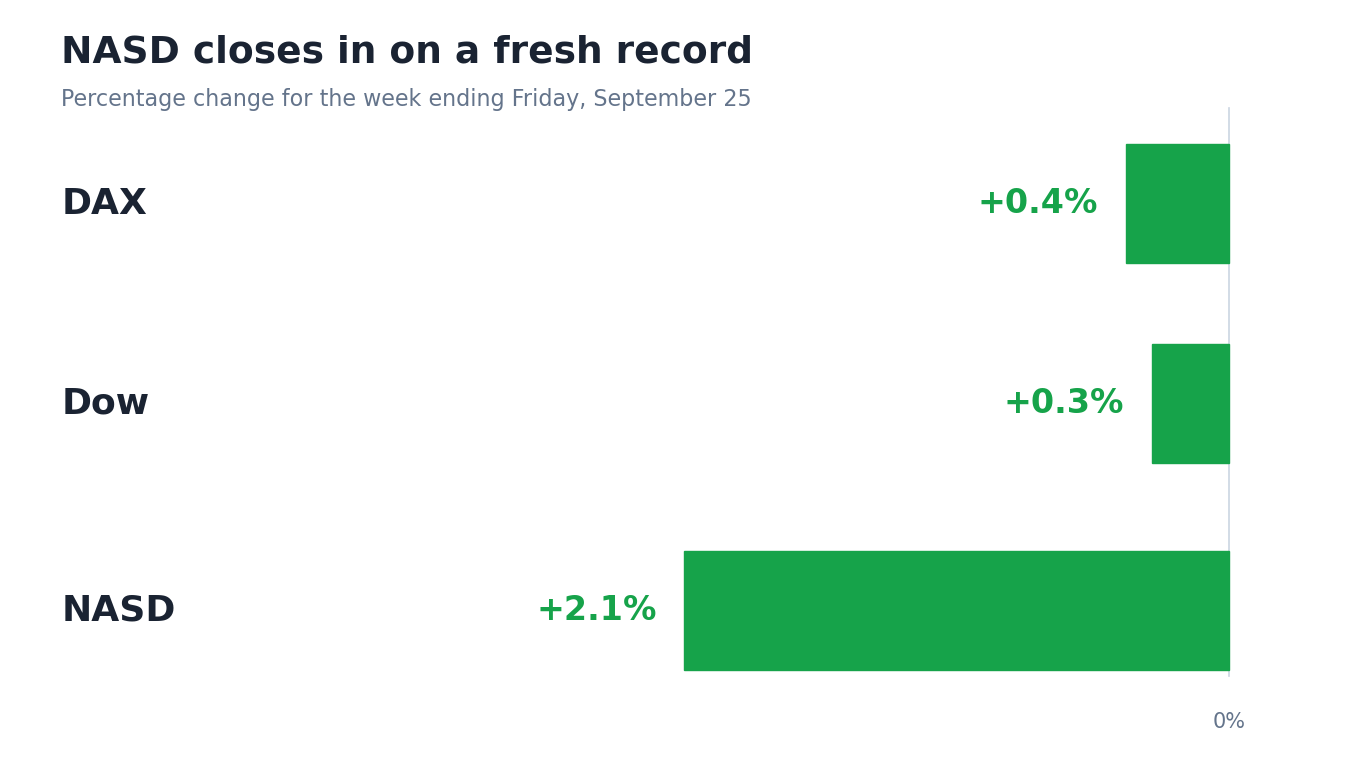
It was a choppier week than the closing numbers suggest. Bond yields surged again in the middle of the week, unsettling all three indices for a day or two, before oil prices eased and an AI-driven rally in chip and tech names pulled everything back up by Friday. NASD did more than recover: Meta, AMD, and Intel led it to a fresh all-time high close mid-week, and it finished Friday just a fraction of a percent below that record. Dow, meanwhile, snapped a three-week losing streak.
Last week
DAX added 0.4% to close at 25,408.64, Dow gained 0.3% to 51,828.62 on a strong 478-point Friday, and NASD jumped 2.1% to 27,068.72. NASD’s gain came almost entirely from a two-day burst - a fresh closing record of 27,244.28 and an intraday high of 27,288.79, both set midweek - as investors piled back into the same AI and chip names that have driven most of this year’s tech gains.
The week ahead
DAX
DAX has support around 25,120 and resistance around 25,740, with 26,500 - and fresh record territory beyond it - the bigger target if that clears. There’s little Germany-specific news due this week, so the index is likely to keep taking its cue from Wall Street’s own reaction to Thursday and Friday’s US data. A close below 25,120 would point further down; clearing 25,740 would put the index back on track toward its own highs.
Dow
Dow has support around 51,195 and resistance around 52,390, with its record high of 54,349 still standing well above both. Friday’s rebound came from the same yields-easing, oil-easing combination lifting everything else, so this week’s jobs data matters more here than almost anywhere else - rate-sensitive sectors like banks and industrials react fastest to anything that changes the outlook for borrowing costs.
NASD
NASD has support around 26,754 and resistance around 27,336 - just above its own record close of 27,244.28 and the week’s intraday high of 27,288.79. This is about as close to a real breakout as the index has been all year: clearing that would open new territory outright, while a slip back below 26,754 would suggest last week’s rally ran ahead of itself. Given how much of this move rests on a handful of AI and chip names, a soft earnings surprise from any of them could hit NASD harder than the other two.
Elsewhere this week
Oil eased to around $102.75 a barrel on Friday on reports of progress toward defusing the Strait of Hormuz standoff, only for that progress to unravel again first thing this week: Brent jumped back above $105 after the US rejected Iran’s latest proposal to reopen the strait, pulling equity futures lower with it on Monday morning. Gold held around $4,341 an ounce, still recovering from the low it hit two weeks ago. Bitcoin traded near $84,000, extending its own recovery. EURUSD slipped toward the 1.1375 area as the dollar stayed firm.
The calendar
Congress passed a stopgap funding bill through 11 December, removing the government-shutdown risk that had been hanging over the last day of the month - one less thing for markets to price in going into an unusually busy data week. Monday and Tuesday are quiet by comparison. Wednesday carries the usual mid-week data flow but nothing central. Thursday brings August’s core PCE reading, the Fed’s own preferred inflation gauge, last seen at 3.3% year-on-year and still well above its 2% target. Friday is the real event: September’s jobs report, expected to show a sharp slowdown from August’s 162,000 to something closer to 50,000 by some estimates. A number that soft, so soon after the Fed’s first rate rise in three years, would raise real questions about whether the central bank can keep raising rates without a labour market that’s already cooling faster than it looks.
Nothing on this page is financial advice. Levels and views here are a starting point for your own analysis, not a signal to trade.