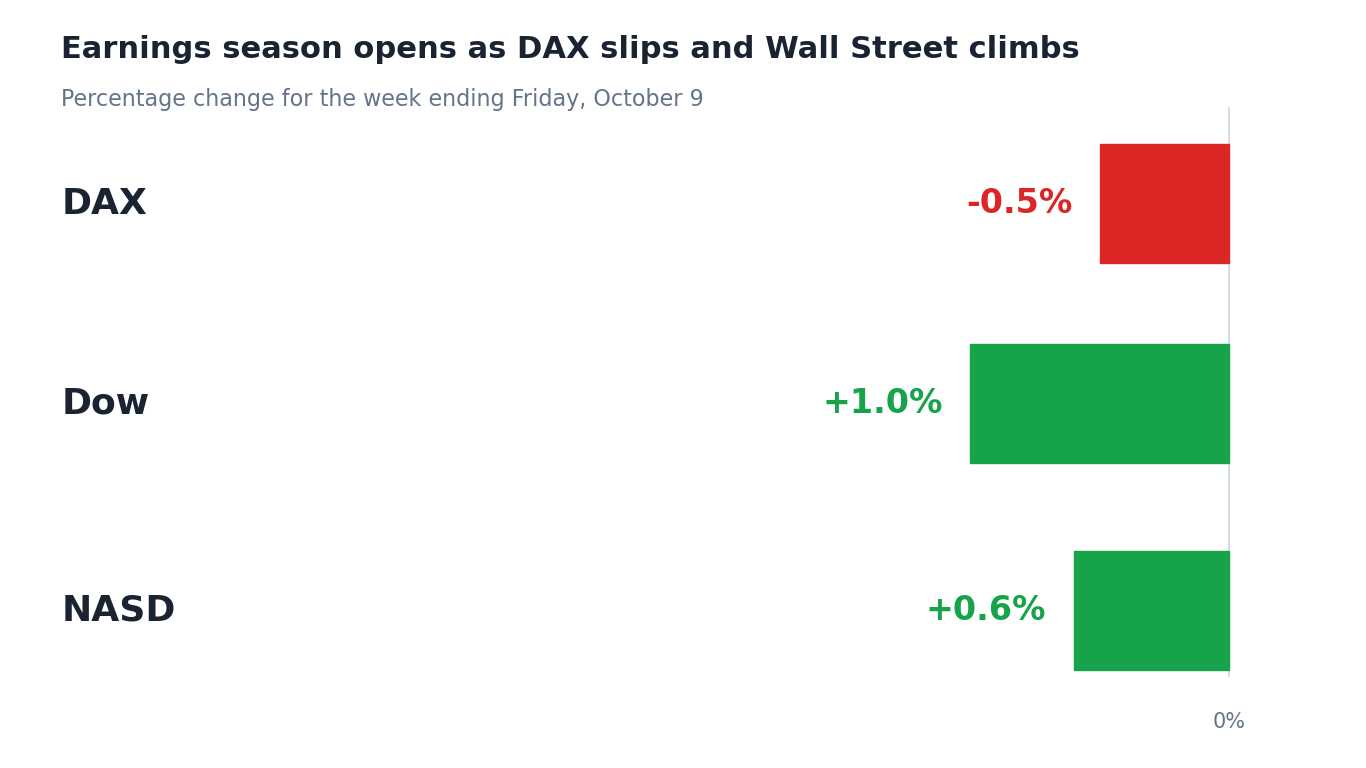
Oil and bond yields did most of the driving last week. Both climbed hard through midweek, pulling every index lower with them, before a comment from President Trump ruling out a strike on Iran before next month’s midterms sent oil down again on Friday. That eased the pressure just in time for Dow and NASD to close the week higher. DAX didn’t get the same lift: it had already dropped below 25,000 on Thursday, its lowest level since July, and Friday’s 1.1% bounce wasn’t enough to turn the week positive.
Last week
DAX fell 0.5% to close at 25,087.27, even after a 1.1% rally on Friday led by Zalando, SAP and Siemens. Dow gained 1.0% to 51,655.01, its best week since early August. NASD added 0.6% to 27,366.17. S&P 500 touched a fresh intraday record of 7,844.52 during the week before easing back as the bond sell-off pushed the 10-year Treasury yield to its highest level since 2002.
The week ahead
DAX
DAX has support around 24,746 and resistance around 25,475. There’s little Germany-specific news due this week, so the index is likely to keep tracking the same oil and yield moves driving Wall Street. A close below 24,746 would put the index back near Thursday’s two-month low; clearing 25,475 would point back toward the levels it held through most of September.
Dow
Dow has support around 51,090 and resistance around 51,992, with its record high of 54,349 still well above both. Banks kick off third-quarter earnings season on Tuesday, with JPMorgan, Goldman Sachs, Wells Fargo and Citigroup all due to report, and several of them are Dow components. A strong set of results could carry the index toward that resistance band; a weak one would hand back some of last week’s gain quickly.
NASD
NASD has support around 27,048 and resistance around 27,704, with its own record close of 27,244.28 and intraday high of 27,353.68 both now comfortably inside that range. Wednesday’s inflation data matters most here, since a hot reading would revive the same borrowing-cost worries that have weighed on richly valued tech names all year. A close above 27,704 would be a clear sign the index is breaking into fresh territory, not just drifting near its old highs.
Elsewhere this week
Oil eased to around $103 a barrel for Brent and $90 for WTI on Friday, after Trump’s comment on Iran took some heat out of the Strait of Hormuz story. Gold rose to around $4,194 an ounce, continuing its recovery. Bitcoin held near $82,800. EURUSD traded around 1.12 as it worked toward resistance in the 1.125 area.
The calendar
Monday is Columbus Day in the US. The bond market is shut, but stock exchanges stay open, so equities still trade on a quiet data day. Tuesday marks the start of third-quarter earnings season, led by the big banks. Wednesday brings September’s US CPI, expected to show inflation ticking up on both the headline and core readings from August. Thursday is the busiest day on paper: September retail sales, producer prices, weekly jobless claims and the Philly Fed survey all land together. With earnings and inflation data arriving in the same week, Wednesday’s CPI print is likely to set the tone for how the market reads everything that follows it.
Nothing on this page is financial advice. Levels and views here are a starting point for your own analysis, not a signal to trade.